After a leak or a flood, the question comes fast: will insurance cover this? In California, the answer usually turns on a single distinction that surprises a lot of homeowners — and getting it right can be the difference between a paid claim and a denied one.
Let us walk through what a standard California homeowners policy typically covers for water damage, what it usually does not, and how to file so your claim has the best chance of approval. This is general information, not legal or insurance advice — your own policy is the final word, so read it and ask your agent about anything unclear.
The rule that decides most claims: sudden and accidental vs. gradual
Most standard policies cover water damage that is sudden and accidental, and exclude damage that is gradual or the result of neglected maintenance. A pipe that bursts without warning is sudden. A supply line that seeped behind a wall for eight months is gradual. Same water, very different outcome on your claim.
That is why fast action and good documentation matter so much. The sooner you report and mitigate, the easier it is to show the loss was sudden rather than something that festered.
A helpful way to picture it: insurers ask whether a reasonable homeowner could have seen it coming and prevented it. A pipe that bursts in the night is bad luck. A faucet that dripped under the sink for a year, warping the cabinet, reads as deferred maintenance. The first is the kind of risk a policy is built to cover; the second is treated as upkeep that was your responsibility.
What is typically covered
- A burst or ruptured pipe.
- A sudden appliance failure — a water heater, dishwasher, or washing machine that fails without warning.
- Rain or storm water entering through sudden damage, like a roof opened up by a windstorm.
- Water damage from putting out a fire, and often the water damage caused by a covered event.
In these cases the policy generally pays to dry the structure and repair or replace what the water ruined, minus your deductible.
The payout usually covers both the direct water damage and the cost to dry the structure, then the repair or replacement of what was ruined — flooring, drywall, cabinetry — up to your limits and minus your deductible. Many policies also cover reasonable additional living expenses if the home is temporarily unlivable during repairs.
What is typically NOT covered
- Flooding from outside — rising water, surface runoff, and creek overflow. That requires separate flood insurance, which we cover in our guide on flood insurance versus homeowners insurance.
- Sewer or drain backups, unless you have added a specific backup endorsement to your policy.
- Gradual leaks, seepage, and anything blamed on deferred maintenance or wear and tear.
- Damage from a leak you knew about and did not fix.
- Mold, in many policies, unless it resulted directly from a covered water loss — and even then coverage is often capped.
It is worth reading these exclusions closely, because they are where most denied claims come from. If you have an older home, a creek nearby, or a history of slow leaks, the gaps in a standard policy are exactly the risks most likely to hit you — and the ones worth closing with an endorsement or a separate flood policy before the wet season.
You have a duty to prevent further damage
Nearly every policy requires you to take reasonable steps to stop the loss from getting worse — shutting off the water and arranging extraction and drying. Wait too long and the insurer can deny the added damage as your responsibility. Acting fast is not just smart, it is part of the contract.
The homeowner's duty to mitigate
That duty-to-mitigate clause is the part homeowners most often overlook. It means calling for extraction and drying promptly is protecting your claim, not jumping the gun. Keep receipts for anything you spend on emergency mitigation — tarps, a plumber's after-hours visit, professional water removal — because those costs are frequently reimbursable. Our emergency water removal service is built for exactly this window.
Mitigation does not mean guessing at permanent repairs. It means stopping the source and preventing further harm — shutting the water off, extracting standing water, and starting the drying. Hold off on full reconstruction until the adjuster has agreed on scope, but never wait on the emergency drying, which the policy expects you to handle promptly.
Water damage right now? Don't wait.
45-minute average dispatch across Murrieta • available 24/7 • licensed & insured
How to file a water damage claim in California
- Stop the source and make the home safe — shut off the water and the power to wet areas.
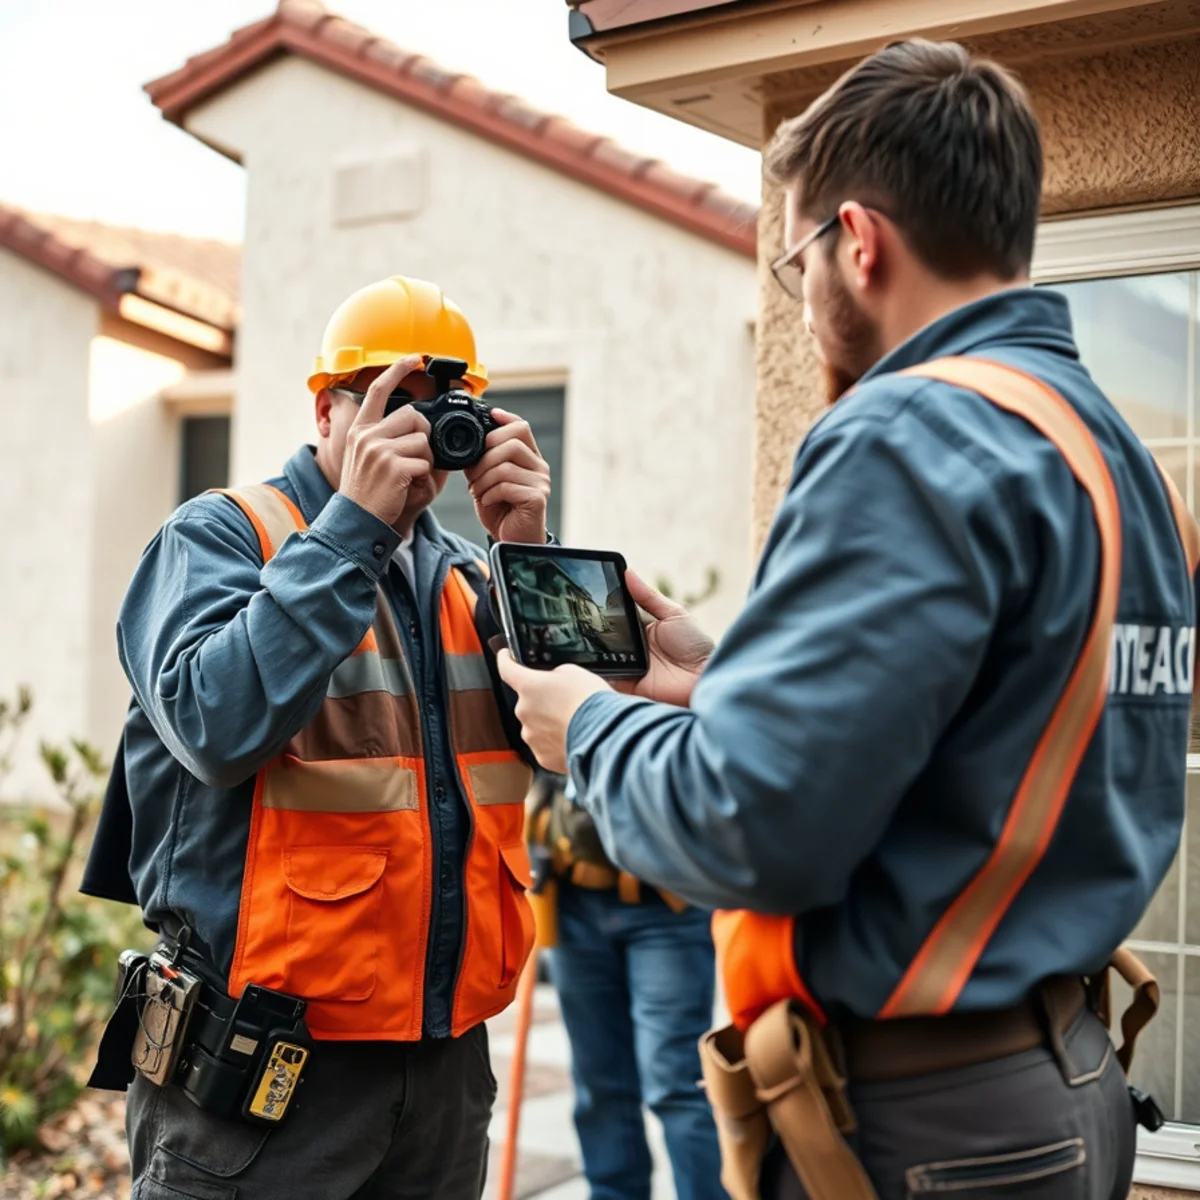
- Document everything before cleanup: photos and video of the source, the standing water, and every damaged item.
- Report the claim to your insurer promptly and get your claim number.
- Mitigate right away by arranging professional extraction and drying, and keep all receipts.
- Keep damaged materials and failed parts until the adjuster has seen them, if it is safe to do so.
- Get a written scope and estimate from your restoration company to compare against the adjuster's.
A few California-specific notes
California generally gives insurers deadlines to acknowledge and respond to claims, and you have the right to a clear explanation if a claim is denied. If your loss involved sewage or outside water, coverage hinges on those endorsements and separate flood policies mentioned above. And if you and the adjuster disagree on scope, an independent written estimate from your restoration contractor is your best tool for the conversation. Our residential water damage restoration team documents each project in the detail adjusters expect, and we serve Murrieta, Temecula, and the surrounding Riverside County communities.
One detail that affects your payout is whether your policy pays replacement cost or actual cash value. Replacement cost pays what it takes to replace damaged items new; actual cash value subtracts depreciation, so an older floor or roof pays out less. Knowing which you have before a loss prevents an unwelcome surprise at claim time.
The bottom line
Most sudden water losses are covered in California; most gradual ones are not; flood and sewer backup need their own coverage. The homeowners who fare best act fast, document thoroughly, and mitigate the damage as their policy requires. Again, this is general information rather than legal or insurance advice — check your specific policy and talk to your agent. If you need the water handled today, call our 24/7 team and we will document as we go.
Frequently Asked Questions
Usually, if the damage was sudden and accidental — like a burst pipe or a failed appliance. Gradual leaks, neglected maintenance, outside flooding, and sewer backups without an endorsement are commonly excluded. Your own policy language controls, so read it carefully.
Sudden means an abrupt, unexpected failure, such as a pipe bursting. Gradual means a slow leak or seepage that happened over time. Standard policies cover the sudden kind and exclude the gradual kind, which is why fast reporting and documentation help your claim.
Sometimes, but only when it results directly from a covered water loss, and coverage is often capped. Mold blamed on a long-neglected leak is usually excluded. Drying quickly to prevent mold in the first place is the safest route.
Stop the source, make the home safe, document everything with photos and video before cleaning, report the claim promptly, and mitigate by arranging professional drying while keeping receipts. Our documentation checklist walks through the details.
Written & reviewed by the Water Damage Restoration Murrieta team
IICRC-certified, licensed & insured water damage restoration professionals serving Murrieta and southwest Riverside County. Questions about your situation? Call (201) 277-9344 — we answer 24/7.
Serving these areas: